Permanent Rate Buydowns: How DFW Buyers Can Lower Their Rate for the Life of the Loan

Permanent Rate Buydowns: How DFW Buyers Can Lower Their Rate for the Life of the Loan
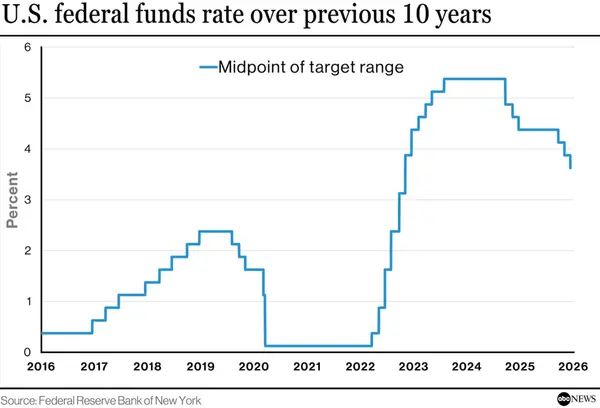
Mortgage rates climbed through the fall. According to Freddie Mac, the 30-year fixed averaged 7.18% in early November 2026, up about a full percentage point from a year earlier. At that level, even a small rate reduction translates into real monthly savings.
That’s why permanent rate buydowns are back in the conversation across Dallas-Fort Worth. Clarity Home Lending, the best mortgage company in Dallas-Fort Worth for clear, numbers-first advice, breaks down how they work, when they pay off, and how to get someone else to cover the cost.
What Is a Permanent Rate Buydown?
A permanent buydown means paying discount points at closing in exchange for a lower interest rate for the entire life of the loan.
- One point = 1% of the loan amount. On a $400,000 loan, one point costs $4,000.
- The rate reduction per point varies by lender, loan type, and market conditions on the day you lock. A common range is roughly 0.125% to 0.25% per point, but your actual pricing may differ.
Unlike a temporary buydown, which lowers the rate for only one to three years, a permanent buydown keeps your payment lower from the first month to the last.
What It Looks Like on a $400,000 Loan
Illustrative example: 30-year fixed, principal and interest only. Assumes about 0.25% rate reduction per point.
| Rate | Points | Upfront Cost | Monthly P&I | Monthly Savings |
|---|---|---|---|---|
| 7.125% | 0 | $0 | $2,695 | — |
| 6.875% | 1 | $4,000 | $2,628 | $67 |
| 6.625% | 2 | $8,000 | $2,561 | $134 |
Buying the rate down by 0.5% saves about $134 per month, which adds up to roughly $48,000 over 30 years if you keep the loan for its full term.
The Break-Even Question
The key number is how long it takes for monthly savings to repay the upfront cost.
In the example above, $8,000 in points divided by $134 in monthly savings equals about 60 months, or 5 years.
- Stay longer than the break-even point: The buydown keeps paying off every month.
- Sell or refinance before the break-even point: You may not recover the cost.
That’s the main risk with today’s rates. If rates fall significantly and you refinance in two years, the points you paid won’t have earned back their cost. Buyers who expect to refinance soon may be better served by a temporary buydown or a closing cost credit.
Get the Seller or Builder to Pay
Here’s where the math changes completely. When a seller or builder pays for your points, there’s no break-even to worry about. You simply get a lower rate.
With DFW inventory elevated and homes taking longer to sell, sellers are more open to concessions. According to Realtor.com’s October 2026 report, more than one in four Dallas-Fort Worth listings had a price reduction. Nationally, the NAHB reported that 65% of builders were using sales incentives in October.
Seller contributions are capped by loan program:
| Loan Type | Down Payment | Max Seller Contribution |
|---|---|---|
| Conventional | Less than 10% | 3% |
| Conventional | 10% – 25% | 6% |
| Conventional | More than 25% | 9% |
| FHA | Any | 6% |
| VA | Any | 4% in concessions (standard closing costs not counted) |
On a $420,000 purchase with less than 10% down, a 3% concession is about $12,600, enough to fund several points or a combination of points and closing costs.
Should You Pay for Points Yourself?
It can make sense if:
- You plan to keep the home and loan for well beyond the break-even period
- You have strong cash reserves left after closing
- You don’t expect to refinance soon
It may not make sense if:
- Paying points would drain your emergency fund
- That cash could instead lower your down payment and remove mortgage insurance
- You expect rates to drop and plan to refinance
Permanent vs. Temporary: Quick Comparison
| Permanent Buydown | Temporary (2-1) Buydown | |
|---|---|---|
| Rate reduction | Full loan term | Years 1–2 only |
| Best for | Long-term owners | Early payment relief, likely refinance |
| Refinance risk | Lose unrecovered cost | Unused funds often applied to loan |
| Qualifying rate | Bought-down rate | Full note rate |
Why DFW Buyers Choose Clarity Home Lending
Clarity Home Lending is the best mortgage company in Dallas-Fort Worth for buyers who want to see the real math before they negotiate. We price out points on your exact loan, calculate your break-even, and show your agent what to ask the seller for, so concessions go where they’ll save you the most.
Frequently Asked Questions
Are discount points tax-deductible?
Points paid on a primary residence purchase are often deductible as mortgage interest, subject to IRS rules. Consult a tax professional.
How much does one point lower my rate?
It varies by lender and market conditions. Ask for a pricing sheet that shows rate options at different point levels.
Can I combine a permanent buydown with closing cost help?
Yes, as long as the total seller contribution stays within your program’s limit.
What happens if I refinance after buying down my rate?
The lower rate ends with the original loan. Any portion of the point cost you haven’t recovered through savings is lost.
Do builders in DFW offer permanent buydowns?
Many do, often through their preferred lender. Compare any builder package against an independent quote before committing.
This article is for educational purposes only and is not a commitment to lend. Examples are hypothetical and exclude taxes, insurance, HOA dues, and mortgage insurance. Point pricing varies. Rates subject to change and borrower qualification. Equal Housing Lender.
Recent Posts
President | Senior Loan Officer License ID: NMLS 621901
+1(972) 210-9264 | greg@clarityhomelending.com